
In the midst of market turmoil, many investors are turning to precious metals like gold – but is it a safe investment?
Recently, Partner and Chief Investment Officer John Ingram shared his thoughts with WSJ
Read the full story here

In the midst of market turmoil, many investors are turning to precious metals like gold – but is it a safe investment?
Recently, Partner and Chief Investment Officer John Ingram shared his thoughts with WSJ
Read the full story here

Why waiting to implement your plan can reduce the benefits of your gift to your charity and you.
We all start off with the greatest of intentions: fold and put away the laundry once it’s out of the dryer, call our loved ones to see how they are doing, volunteer, start that company, and take that family vacation.
The reality is that many of us wait until the last minute, and as a result we either don’t get the full benefit of our actions or even worse wait until it is too late. The same goes for charitable giving.
Below are some ways you can act now and still have a greater impact than if you waited.
Qualified Charitable Distributions (QCDs). These allow individuals to donate up to $100,000 total to one or more charities directly from their IRA. This means you are able to start making tax-free distributions to the 501(c) (3) charity of your choice at age 70.5, which can lead to significantly more money to the causes you care about and help reduce your taxable income over your lifetime.
It’s important to get started on these distributions early and throughout the year because the distribution must be received by the charity before the end of the calendar year in order to qualify. Married couples can each donate $100,000 for a total of $200,000!
“Bunching.” This is the practice of front-loading many years of charitable giving into one tax year. Many taxpayers don’t have the necessary deductions to surpass the standard deduction threshold established by the Tax Cuts and Jobs Act in 2017.
However, you can still receive a tax benefit by “bunching” multiple years’ worth of charitable giving in one year to surpass the itemization threshold. This can be especially useful in years when you have a significant taxable event. Plus, many people like the idea of creating a legacy gifting account.
Don’t want to make such a large contribution to one charity in a year? This is where the use of a Donor Advised Fund or “DAF” can be helpful. You can make a large gift to your DAF in one year, get the maximum tax deduction, then spread out the distributions to charity over multiple years and even have the potential of the DAF to grow over time which allows for even greater gifting power.
Gifting of business ownership before you exit. Congratulations! All your years of learning and earning have led to a successful business you are looking to exit so you can enter the “serve” phase of your life. Starting your business took years of planning and preparation – and so does getting ready to exit your business in a way that achieves maximum rewards and makes the greatest impact.
Unfortunately, many business owners wait until AFTER the sale of their business to consider how to support the causes they serve and miss a tremendous opportunity to incorporate charitable giving before they exit.
Consider gifting shares of your privately held business before you exit. This allows you to get a deduction of up to 30% of your adjusted gross income at the time of the gift. More importantly, because the charity doesn’t pay taxes when the shares are sold, they get to keep the full amount of the gift!
To fully maximize this opportunity, it takes time and preparation and there are a number of tips you need to consider throughout this process:
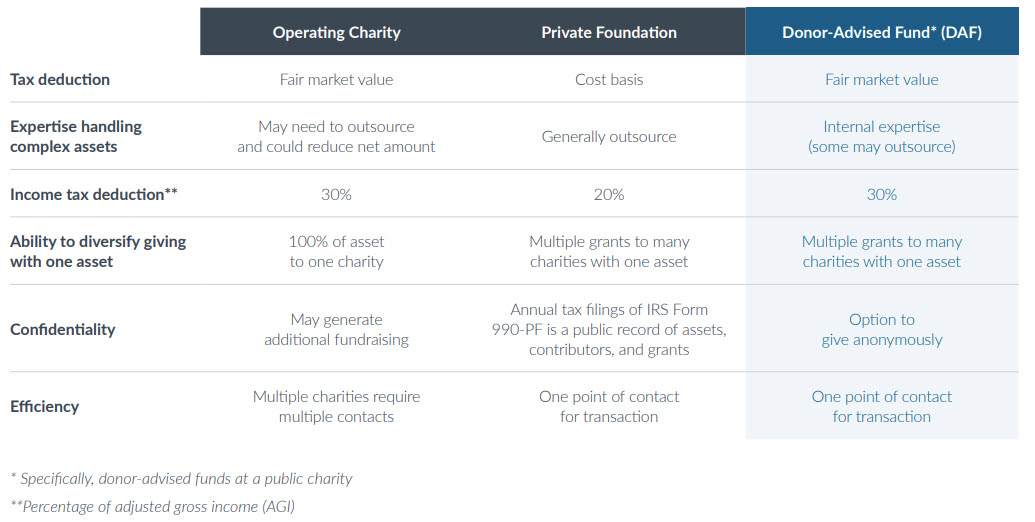
Source: Fidelity Charitable.
There are many ways to support the causes you care about. Whether it is through volunteering or making a financial impact, once you find what resonates with your values it is important not to hesitate to act.
If you want to learn more about what charitable strategies you might benefit from, please DON’T HESITATE to contact us at Crestwood Advisors.

Crestwood Advisors is pleased to announce that we have again made this year’s Financial Advisor Magazine’s 2023 RIA Survey & Ranking list! Congratulations to our entire team for their efforts that made this possible.
View the entire list here.
Please view Crestwood Advisors’ list of important disclosures regarding awards and recognitions here.

FOR IMMEDIATE RELEASE
Boutique RIA firm continues expanding its New England team as part of strategic growth plan
Boston, Mass. (July 11, 2023) – Crestwood Advisors (“Crestwood”), a boutique investment advisory and wealth management firm with offices in Boston and Fairfield County, Connecticut, is pleased to announce continued regional growth with Katie Sheehan joining the team.
Katie joins Crestwood as Managing Director and Wealth Strategist based in the firm’s Boston office. She brings a wealth of experience to her new role, having previously worked as a Wealth Strategist at SVB (formerly Boston Private) and as a Partner at DesRosiers, Tierney & Sheehan, LLC.
Her legal career focused on estate planning, trust administration, charitable planning, long-term care planning, and elder law. Katie holds a bachelor’s degree from Boston College and a law degree from Suffolk University Law School.
“We are thrilled to welcome Katie Sheehan to the firm,” said Crestwood CEO/Managing Partner Michael Eckton. “Her extensive financial services expertise and impressive track record in the industry make her a valuable addition to our growing team. Her deep knowledge and strategic insights will undoubtedly strengthen our ability to deliver exceptional wealth management solutions to our esteemed clients.
Comprising a dedicated group of around 50 financial planning and investment experts in New England, Crestwood is committed to assisting individuals and families in attaining their financial objectives. The firm’s primary goal is to offer personalized financial solutions and advice that caters to its clients’ distinctive requirements and situations, thereby promoting their prosperity and financial well-being.
Since the beginning of 2021, the Crestwood team has expanded by approximately 20 percent, enhancing the firm’s ability to provide exceptional service, expertise, experience, and a commitment to excellence to new clients in the local market.
###
About Crestwood Advisors
Crestwood Advisors is an independent, fee-only, wealth management firm with over $4 billion in assets under management. Founded in 2003, Crestwood Advisors provides investment management with financial planning strategies to help high-net-worth individuals and families identify and prioritize their goals and build sustainable wealth so that they may enjoy more financially secure and purposeful lives. For more information, please visit https://www.crestwoodadvisors.com.

Good news! Inflation is beginning to show signs of slowing down. However, that does not mean you should give up your financial savings habits.
Peter T. Malone, CFA, CFP, Director and Portfolio Manager at Crestwood Advisors, spoke with Yahoo Finance on financial mistakes people should avoid when it comes to inflation.
Click here to read the full article

How to leverage income tax credits for renewable energy, home improvements and EVs
The Inflation Reduction Act (”the Act”) of 2022 marks a pivotal moment for individuals seeking to contribute to a more sustainable future, while simultaneously reducing their income tax liability.
This legislation, with a focus on reducing carbon emissions today and creating a more energy-abundant future, also includes substantial revisions and enhancements to income tax credits associated with renewable energy, home improvements, electric vehicles (EVs) and electric bikes.
Individuals stand to gain substantially from these incentives if they understand how to use them effectively. Here, we offer a high-level guide to navigating the landscape of these tax credits.
Rooftop Solar
Originally established in 2005, the Investment Tax Credit, commonly known as the Federal Solar Tax Credit, provides a tax incentive for solar photovoltaic (PV) installation. Under the Act, this tax credit was extended and enhanced. The current benefit is 30% of the value of your installed rooftop solar system.
With the cost of an average home system running around $15,000, this tax credit could be worth over $4,000 or more. The credit is uncapped, so the larger your system, the larger your benefit.
Heating & Cooling
The Act also offers expands tax credits for energy-efficient home improvements. This includes but is not limited to, energy-efficient windows and doors, insulation, HVAC systems, and certain types of roofing. For individuals with one or more properties, this can result in substantial tax savings. It also presents an opportunity for individuals to enhance the value of their properties while reducing their carbon footprint.
Electric Vehicle Tax Credits
The Act provides tax credits available for the purchase of new EVs and may allow an individual to upgrade their transportation method to more sustainable option while also benefiting from a tax break. While qualifying for the credit is somewhat complicated, here are a few takeaways:
Notably, the Act removes the manufacturer cap previously associated with the electric vehicle tax credit. Now, no matter how many electric vehicles a manufacturer sells, customers can still receive the full tax credit, which makes high-end electric vehicles a more financially attractive option.
The Act has opened new avenues for individuals to mitigate their tax liabilities, support renewable energy, and make sustainable choices in their personal lives. By investing in renewable energy, making energy-efficient home improvements, and choosing electric vehicles, these individuals can align their financial strategies with a sustainable future.
If you want to learn more about what tax credits you might benefit from, there are many websites that provide education and assistance. Two helpful ones are Rewiring America and the IRS.

Regional bank stocks have tumbled due to the recent instability of the banking sector. So, here’s the big question: are they a good buy?
Crestwood CIO John Ingram spoke with Money about investing in bank stocks.
Read the full article here

Nicole DellaPasqua, a certified financial planner at Crestwood Advisors in Boston, spoke with Financial Planning about financial planners working from home and the best practices they can put in place to make remote work successful.
Learn how to mitigate the remoteness of remote work by reading the full article here

At the beginning of each year, individuals set personal, professional, or financial goals for themselves. How often do you revisit these goals, and what have you accomplished thus far? As we approach the second half of the year, we urge you to revisit your goals and all that you hoped to accomplish for 2023. While we may not be able to guide you with your personal goals, we can help accelerate your 2023 financial goals across the finish line.
Financial Plan: Are you on track?
Goal Review: Over time, plans may change. It is important to review your goals regularly to ensure you are still on track for your short-term and long-term objectives. Has a life-changing event occurred? Is retirement around the corner? Reevaluating what is important to you and discussing how this impacts the next 2, 5, or 10+ years is crucial. While these are evolving conversations, it is essential to make sure your financial plan accurately depicts your idea and vision of the future!
Commitments to Saving & Investments: Have you followed your plan?
Retirement Contributions: Make sure that you have adjusted your contributions to maximize your savings for 2023. The maximum amount you can contribute to your 401k in 2023 is $22,500 (plus an additional $7,500 if you are 50 or older by the end of the year). If you do not have a 401k, we can help evaluate your options for saving toward retirement.
Monthly Savings: Periodic additions to investment accounts are a great way to compound growth and take advantage of investment opportunities as they arise. Stay committed to saving above and beyond contributions to retirement accounts. This will help grow your portfolio when you need it most. Whether it is following a monthly budget or setting up an automatic transfer to your investment accounts, putting aside any amount is beneficial.
Debt Repayment: Are there changes to be made?
Given the current interest rate environment, now is the time to review your goals for paying down any outstanding debt or other liabilities. While we are uncertain of where rates will go in the future, the recent increase has affected cash flow for many individuals with fluctuating lines of credit, margin balances, or adjustable-rate mortgages. Talk to us about your perspective on maintaining a debt balance, and let’s develop a plan to pay off your liabilities strategically.
Charitable Goals: What are your intentions?
Many people have goals of gifting to charities annually. Rather than waiting until the end of the year and rushing to make gifts, consider a monthly or quarterly donation to causes you feel most passionate about. What is your tax picture for the year? Consider your intentions for gifting and review what you have accomplished. We can help you decide how to gift and what assets are most appropriate to gift.
Items to Review: What is on the back burner?
Now that the 2022 tax season is behind you, please send us a PDF copy of your 2022 tax return. With a copy of your tax return, we may identify tax planning opportunities and help facilitate conversations with your tax preparer.
If it has been a while since you last reviewed your estate plan, there may be outdated items that should be revised. Ensure that the named individuals in your estate plan are still the most appropriate choices (ex. Healthcare Proxies, Powers of Attorney, or Trustees). We can help review your current plan, identify areas of shortfall, and make changes to titling or beneficiaries as directed.
Review your insurance coverage and consider any changes that are needed. If you have policies that have not been reviewed for many years or that may need to be adjusted, we can connect you with an agent who can provide comparisons to other policies, review any shortfalls in your current coverage, and evaluate the cost-efficiency of making a change.
Improve your odds for a successful year! The first step is evaluating the goals which you set to accomplish in 2023. The second step is to let Crestwood help you! Let’s end 2023 with a bang and accomplish all that you set out to complete! Your team is here to help.

Our CIO John Ingram, spoke with Yahoo Finance about the downward trend of inflation for 2023. The good news is experts are seeing a decline in inflation, consumers are just wanting to know when.
Read the full article here