Life Lessons To Help Build a Solid Financial Foundation

It can be difficult to navigate the complexities of financial management when you’re just starting your career, especially when you live in a high-cost area. Making thoughtful financial decisions early on can support greater flexibility and security down the road. The three foundational lessons below can help lay the groundwork for financial resilience and long-term confidence.

“Expecting the unexpected is not just a mindset; it’s a passport to the thrilling destinations of life’s journey.” — Simon Sinek
Life is full of surprises. Building an emergency fund is a key first step in financial planning. Aim to set aside 3-6 months of essential living expenses in a high-yield savings or money market account. This fund should serve as a safety net in the event of job loss, medical bills, or other unexpected circumstances life may throw your way, and helps you avoid relying on high-interest debt or personal loans. Start by contributing a small, consistent amount each month, and increase contributions as your income grows. Revisit the fund annually or after major life changes, such as a move, a new job, or increased living costs, to ensure it remains appropriately sized for your needs.

“Someone is sitting in the shade today because someone planted a tree a long time ago.” — Warren Buffet
Look ahead to the life you want and prioritize investing early so there will be adequate financial resources available to help you realize your long term goals. While it can be tempting to focus on short-term spending, building lasting financial security starts with discipline and consistently “paying yourself first” by allocating a portion of your income toward your savings. Crestwood can help you understand the fundamentals of saving and investing.

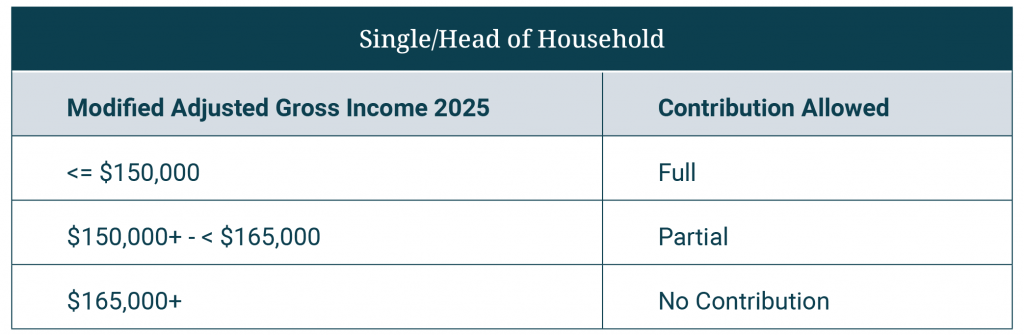
It’s also a good idea to contribute to a Roth IRA early in your career, before your income exceeds the limit, because Roth IRAs offer valuable tax advantages. Since the money you contribute has already been taxed, you are not taxed on qualified withdrawals in retirement, and you will not be required to make withdrawals from that account. If you are younger than 50 years old, you can contribute up to $7,000 into a Roth IRA in 2025, but only if your modified adjusted gross income is below the cut-off.
In addition, try to participate in your company’s 401(k) plan, making sure to contribute enough to take advantage of any available employer match. Some employers will match your savings, fully or partially, up to a designated percentage. This is essentially free money toward your retirement. A common rule of thumb is to save approximately 10% – 15% of your salary for retirement, including a match from your employer. However, be sure to understand the vesting schedule on matched funds, which may require you to stay employed for a certain number of years before the company’s contributions fully belong to you.

“Real change, enduring change, happens one step at a time.” — Ruth Bader Ginsburg
Actively managing your career development and creating a financial plan for the future can help put the odds in your favor. In your career, continue to diversify your experience and develop transferable skills such as writing, analytics, and project management. In addition, leverage employer-sponsored development programs and network internally and externally to build connections that expand your options.

Reach Out to Crestwood
We help clients and their families make sound decisions for the future and protect wealth through every life stage. If you or a loved one is just starting out, we would be happy to have a conversation to help them build a plan tailored to their goals.

If you are not yet a Crestwood client, please contact us to see how we can help you and your loved ones realize their dreams.

This document is provided for general informational purposes only by Crestwood Advisors, an investment adviser. Crestwood Advisors does not provide legal advice, and this document should not be construed as containing legal advice. For legal advice, consult with a licensed attorney. This document should not be construed as containing tax advice. For tax advice, consult with your tax adviser.

August Economic Update: Shooting the Messenger (Even if the Message Wasn’t All Bad)

A report from the Bureau of Labor Statistics (BLS) released after July’s FOMC meeting showed weaker job growth in the May-July period than previously estimated. Job growth for June and July was significantly revised downward, with 258,000 fewer reported new jobs.  The labor market is feeling the pressures of broad uncertainty, higher tariffs, and reduced immigration.

The reaction was swift: President Trump fired the head of the BLS, the dollar weakened, and equity markets reacted poorly to both the numbers and the firing.

As we have noted in prior Economic Updates, data gathering is a slow process and subject to frequent revision. Further, Fed Governor Waller noted in a speech on July 17 that there was a likelihood of downward revisions when the data was released1. So, for those closely listening to the Fed, the BLS announcement was not completely out of the blue.

Importantly, while the disappointing job growth numbers show that economic activity is slowing, the data also support the case that the job market is still generally healthy.  The weaker data increases the odds that the Fed cuts interest rates during its next meeting on September 17.

Divergence of Opinions at the FOMC
At its July 30 meeting, the Federal Open Market Committee (FOMC) opted to hold the federal funds rate at 4.25% – 4.50% for the fifth consecutive session. The recurring theme behind the Fed’s decision to leave rates unchanged has been persistent uncertainty.

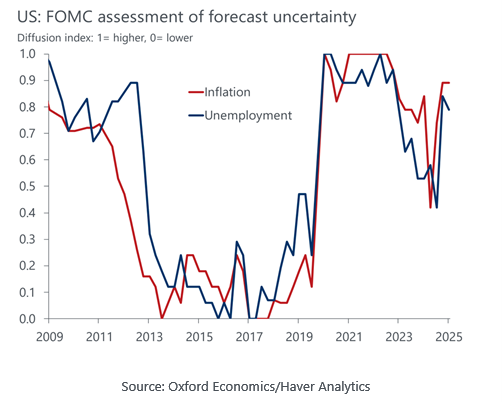
The FOMC Diffusion Index (shown below) captures the distribution of individual FOMC participants’ judgments about economic forecasts like GDP, inflation or unemployment. The chart shows that index levels have risen significantly this year. In fact, they are reaching points not seen since the period surrounding the Pandemic or the years following the Great Financial Crisis of 2008.

In the current environment, it’s not surprising that the decision of the FOMC this time was not unanimous. While individual dissents among Fed governors and presidents of the various Federal Reserve banks are not uncommon, July’s meeting marked the first time since 1993 that two governors dissented from the majority decision. Who dissented is worth noting: Michelle Bowman and Christopher Waller both favored a rate cut now. Their premise was that inflationary pressure from tariffs will be temporary and that risks to employment warrant a cut sooner rather than later.

Readers will note that Waller had signaled his pending dissent weeks in advance in the speech noted above, and Bowman was among the potential candidates to succeed Powell as the next Fed Chair. Their opinions may be foreshadowing the direction of the next iteration of the Fed.

September will be eventful for several reasons:

  1. President Trump has nominated Stephen Miran, often credited as the chief architect of the administration’s tariff policy, to fill the vacancy left by Fed Governor Adriana Kugler’s August departure. In 2024, Miran co-wrote a paper critical of the Fed and argued that governance should be overhauled. Among the recommendations were giving the President the power to remove Fed board members and Reserve Bank leaders at will2. The Senate Banking Committee will hold hearings on Miran’s nomination, which will include questioning him about his qualifications, policy positions, and perspective on the role of the Fed.
  2. The Fed will have several more months of labor market and inflation data to contextualize the effect of tariffs and immigration policy on the US economy.
  3. The FOMC will release an updated Statement of Economic Projections (aka, their “Dot Plot”), which captures the Fed members’ estimates for the range of interest rates over the next few years.

What does this mean for investors?
Investors should continue to expect further economic impact from an evolving tariff policy and reduced immigration as well as deportations. Although their impact on prices and growth can be slow to manifest, their effects inevitably show in data such as the labor market report. Investors should anticipate this and not be taken off guard when data appears to ‘surprise’ the market by showing evidence of this. As always, patience and discipline are the best approaches.

Capital Markets
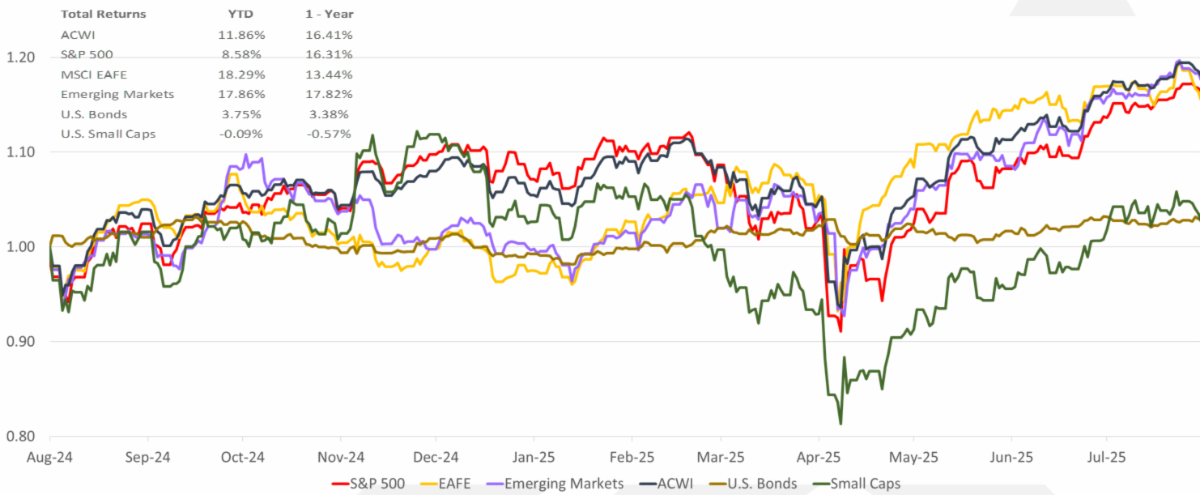
The MSCI All Country World Index (ACWI) rose 1.4% in July. The S&P 500 rose for a third straight month returning 2.2%. The Index is now up 8.6% year-to-date after being down as much as 15% in early April. Developed International equities (MSCI EAFE) weakened, losing 1.4% for the month, while Emerging Markets rose by 2%. US Small and Mid Caps (Russell 2000) rose 1.7%, while bonds were flat.

Source: Bloomberg. EAFE is MSCI EAFE Index(1), Emerging Markets is MSCI Emerging Markets(2) and U.S. Bonds is Barclays U.S. Aggregate(3). ACWI is the MSCI ACWI Index(4). Small Caps is the Russell 2000 Index(5). S&P 500 is the S&P 500 Index(6). The S&P 500 Ex-NVDA/ AVGO represents the S&P 500 excluding the stocks Nvidia and Broadcom, the remaining stocks are then weighted by their market cap. The above information is as of 7/31/2025.


Footnotes:
1: The Case for Cutting Now by Governor Christopher Waller. Full text available at: https://www.federalreserve.gov/newsevents/speech/waller20250717a.htm
2: Reform the Federal Reserve’s Governance to Deliver Better Monetary Outcomes by Dan Katz, Stephen Miran. Full text available at: https://manhattan.institute/article/reform-the-federal-reserves-governance-to-deliver-better-monetary-outcomes

This document contains forward-looking statements, predictions and forecasts (“forward-looking statements”) concerning our beliefs and opinions in respect of the future. Forward-looking statements necessarily involve risks and uncertainties, and undue reliance should not be placed on them. There can be no assurance that forward-looking statements will prove to be accurate, and actual results and future events could differ materially from those anticipated in such statements.